VZ max pain, gamma exposure (GEX) & options open interest
As of close · rank #117 by open interest · 1,399 sessions of history since Dec 1, 2020
VZ's nearest-expiration max pain is 46.00 for 2026-10-16, its GEX flip is 42.84, net GEX is -13,010,080, its put/call open-interest ratio is 0.74. These are whole-chain derived aggregates as of Oct 9, 2026 close.
VZ max pain and GEX snapshot
End-of-day snapshot for . Nearest-expiration max pain uses the expiry shown on its card; GEX uses the whole chain. Missing values are unavailable, not zero.
Prices are in US dollars per share. Net GEX is modeled dollar-delta change per $1 underlying move. Max pain minimizes aggregate intrinsic payout for that expiration; it is not a closing-price forecast. Signed GEX uses calls positive and puts negative, a model convention rather than observed dealer inventory. The flip is a confirmed zero crossing; walls locate side-specific concentrations, not guaranteed support or resistance.
Learn how to read the max pain payout example, GEX chart, gamma flip and walls, and open interest versus trading volume.
Advanced options analysis
Public aggregate analysis from the dated chain, normalized where possible for comparison across tickers. Catalyst intensity measures unusual pricing and activity; it does not identify an event, predict direction, or establish that an investment is attractive.
Strongest relative signals: volume/OI 0.29 · 25Δ risk reversal -154.6 pp · front IV premium 6.3 pp
VZ closed 20.4% below its gamma max of 50.13. It is 5.1% below the delta neutral price of 43.79. Total open interest is 898,915, -1.7% versus the previous session. Its options catalyst-intensity score is 75.4 out of 100, led by volume/OI 0.29, 25Δ risk reversal -154.6 pp, front IV premium 6.3 pp. What gamma max means · What delta neutral means
Call versus put open interest changes
Growth compares outstanding contracts on each side. A positive growth gap favors calls; a negative gap favors puts. Standardized surprises compare each measure with its own prior history. These describe the OI balance, not IV skew or buying direction.
| Measure | Value |
|---|---|
| Call OI change, 1 session | -5,665 contracts · -1.1% |
| Put OI change, 1 session | -9,534 contracts · -2.4% |
| Call minus put OI growth, 1 session | +1.4 pp |
| Call OI change, 5 sessions | +16,220 contracts · +3.2% |
| Put OI change, 5 sessions | +3,817 contracts · +1.0% |
| Call minus put OI growth, 5 sessions | +2.2 pp |
| Daily call OI change surprise | -0.13σ (252 prior changes) |
| Daily put OI change surprise | -0.32σ (252 prior changes) |
| Daily call-minus-put growth surprise | +0.62σ (252 prior changes) |
History
Hover for valuesDrag to panScroll to zoomClick a series to hide it ← → step a session+ − zoomTouch: swipe to pan, pinch to zoom, hold for the crosshair
Analysis visualizations
Daily ticker aggregates through 2026-10-09. Contract-level charts are outside the public dataset.
No matching visualizations.
Aggregate IV history
Chart loads when this section is in view.
What followed prior gamma-max crosses?
Each historical path starts at 0% on the cross date and follows the close for ten subsequent trading sessions. Cohorts use the same direction as labelled and require gamma max to be within 10% of the close on both crossing sessions.
Crosses below gamma max 22 completed Day +10 paths · latest Aug 27, 2026
| Horizon | n | Median | Middle 50% | Above zero | Nominal ≥90% median interval | Confidence floor |
|---|---|---|---|---|---|---|
| Day +1 | 22 | -0.9% | -1.3% to +0.7% | 36% | -1.3% to +0.5% | 0.0% |
| Day +2 | 22 | -0.2% | -1.0% to +0.7% | 41% | -0.9% to +0.6% | 0.0% |
| Day +3 | 22 | +0.6% | -0.8% to +1.6% | 68% | -0.7% to +1.6% | 0.0% |
| Day +4 | 22 | -0.3% | -1.1% to +1.5% | 50% | -1.0% to +1.2% | 0.0% |
| Day +5 | 22 | +0.3% | -0.8% to +2.3% | 50% | -0.8% to +2.0% | 0.0% |
| Day +6 | 22 | +0.8% | -0.5% to +2.3% | 55% | -0.5% to +2.0% | 0.0% |
| Day +7 | 22 | +0.8% | -1.2% to +2.7% | 55% | -1.2% to +2.6% | 0.0% |
| Day +8 | 22 | -0.2% | -1.6% to +1.8% | 45% | -0.6% to +1.3% | 0.0% |
| Day +9 | 22 | +0.2% | -1.3% to +2.2% | 55% | -1.3% to +1.2% | 0.0% |
| Day +10 | 22 | +0.4% | -1.3% to +2.4% | 55% | -1.1% to +2.2% | 0.0% |
Crosses above gamma max 21 completed Day +10 paths · latest Aug 25, 2026
| Horizon | n | Median | Middle 50% | Above zero | Nominal ≥90% median interval | Confidence floor |
|---|---|---|---|---|---|---|
| Day +1 | 21 | +0.3% | -0.1% to +0.9% | 67% | -0.1% to +0.7% | 0.0% |
| Day +2 | 21 | +0.4% | -0.9% to +1.3% | 62% | -0.8% to +1.3% | 0.0% |
| Day +3 | 21 | +0.4% | -1.6% to +2.1% | 62% | -0.3% to +1.8% | 0.0% |
| Day +4 | 21 | -0.4% | -1.0% to +3.1% | 48% | -0.8% to +2.1% | 0.0% |
| Day +5 | 21 | +0.6% | -0.3% to +1.7% | 71% | +0.1% to +1.4% | +0.1% |
| Day +6 | 21 | +0.5% | -0.9% to +1.9% | 62% | -0.4% to +0.6% | 0.0% |
| Day +7 | 21 | +0.7% | -1.8% to +2.6% | 62% | -0.9% to +2.2% | 0.0% |
| Day +8 | 21 | +1.1% | -0.8% to +3.0% | 57% | -0.7% to +2.1% | 0.0% |
| Day +9 | 21 | +0.5% | -2.0% to +2.3% | 62% | -1.2% to +2.0% | 0.0% |
| Day +10 | 21 | -0.0% | -2.0% to +2.5% | 48% | -1.0% to +2.1% | 0.0% |
Returns are close-to-close after the labelled number of subsequent trading sessions. The confidence floor is the closest-to-zero bound of the order-statistic median interval; it is zero when that interval spans zero. Its coverage is nominally at least 90% under independent observations. Historical paths can overlap, so the interval and floor are descriptive uncertainty guides rather than formal coverage guarantees. Historical, not a forecast.
Last 252 sessions
| Sessions closed above gamma max | 6% |
| Gamma max crosses | 16 |
| Delta neutral crosses | 24 |
| Prior-year sessions closer to gamma max | 100.0% of 252 |
| Prior-year sessions closer to delta neutral | 63.9% of 252 |
| Open interest percentile (1y) | 6th |
| Daily open interest change versus prior year | -0.22σ (-15,199 contracts; 252 prior changes) |
| Open interest change, 5 sessions | +2.3% |
| Open interest change, 21 sessions | -21.6% |
| History available | Dec 1, 2020 → Oct 9, 2026 |
Recent crosses
- closed below delta neutral at 41.65 vs 43.79 (-5.1%)
- closed below gamma max at 49.43 vs 49.98 (-1.1%)
- closed above gamma max at 50.25 vs 50.01 (+0.5%)
- closed below gamma max at 47.22 vs 48.24 (-2.2%)
- closed above gamma max at 47.32 vs 47.29 (+0.1%)
- closed above delta neutral at 43.88 vs 43.32 (+1.3%)
- closed below delta neutral at 44.10 vs 45.23 (-2.6%)
- closed above delta neutral at 45.37 vs 44.98 (+0.9%)
- closed below delta neutral at 44.87 vs 45.19 (-0.7%)
- closed above delta neutral at 46.78 vs 45.27 (+3.2%)
In today's screens
Neighbours by open interest
Cite or embed this snapshot
Share the dated 1600×840 image or cite this canonical page. The card contains public derived aggregates, not contract-level quotes.
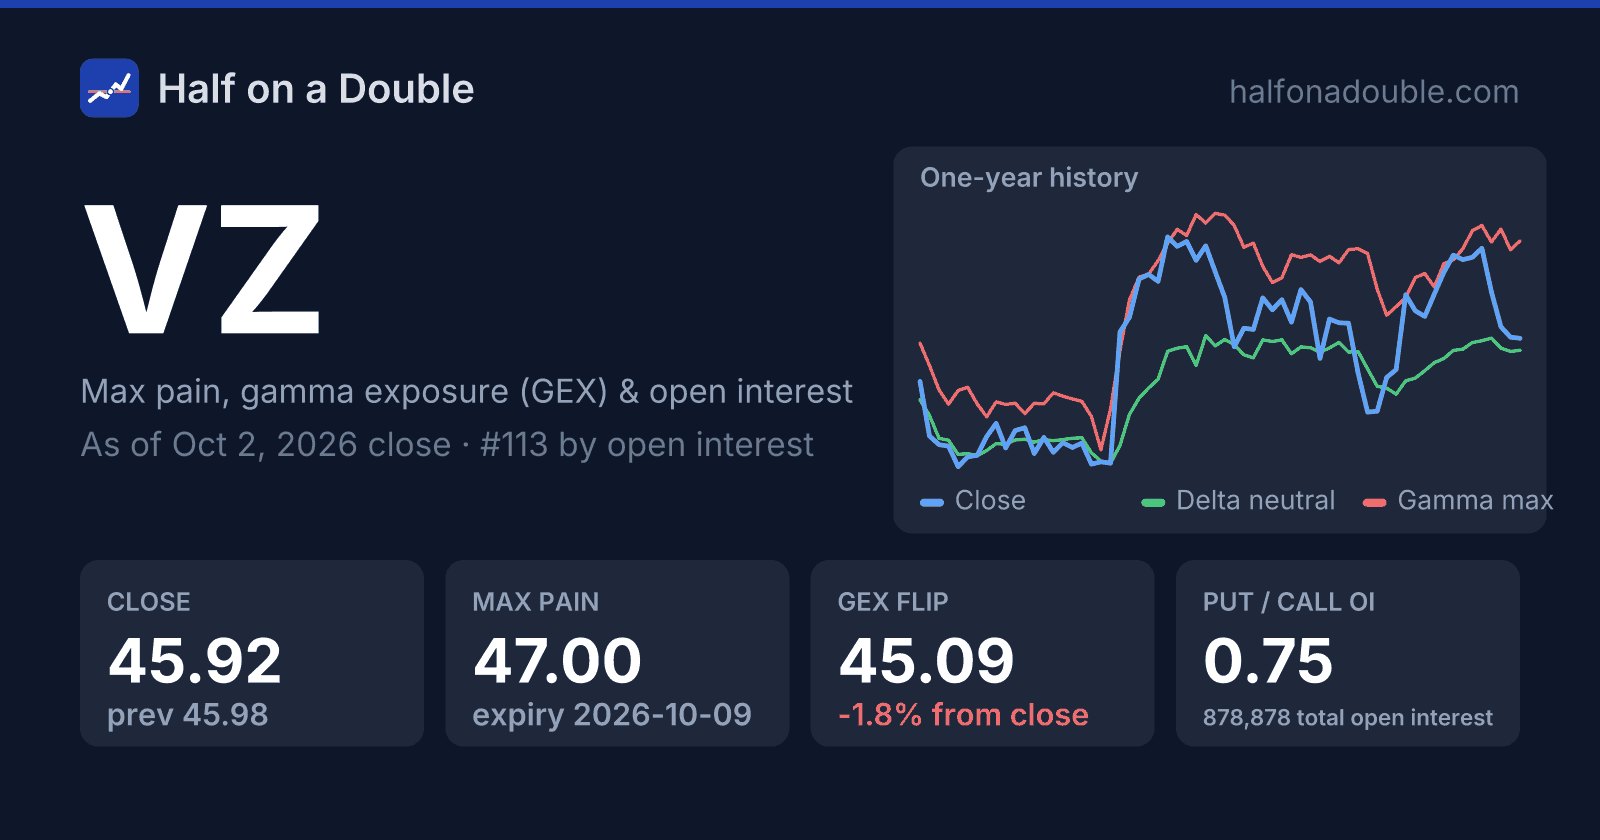
Canonical source: https://halfonadouble.com/stock/VZ
Questions people ask about VZ
What is VZ's max pain for the nearest expiration?
As of Oct 9, 2026 close, nearest-expiration max pain is 46.00 for the 2026-10-16 expiration. It is a payout-minimizing strike for one expiration. An all-expiration pooled value is a different comparison, and neither establishes where the underlying will close. Max pain definition and worked payout example.
Our 2025 max-pain study compares historical Thursday levels with Friday underlying closes and an unchanged-price baseline. Its scope and results are separate from this current ticker snapshot.
What do VZ's gamma exposure and gamma flip show?
Signed net GEX is -13,010,080 as of Oct 9, 2026 close. The confirmed GEX flip is 42.84. These aggregate model outputs use calls positive and puts negative. Their sign does not identify dealers' actual positions or predict the next move. How to interpret GEX, gamma flip and walls.
Where is VZ's gamma max today?
As of Oct 9, 2026, the gamma max for VZ is 50.13, +20.4% from the 41.65 close. Gamma max is the underlying price at which the summed gamma of every open contract is largest; how it is computed and why it matters.
Is VZ above or below its delta neutral price?
VZ closed below delta neutral: 41.65 against a delta neutral price of 43.79. The delta neutral price is where the summed delta of the whole chain is zero; the definition.
How much open interest does VZ have?
898,915 contracts of open interest across 570 listed contracts on Oct 9, 2026, -1.7% versus the previous session. What open interest measures.
Levels are recomputed after every trading day from licensed end-of-day options data; only derived aggregates are published. Methodology · Data and licence · Not investment advice.