SPXW max pain, gamma exposure (GEX) & options open interest
As of close · rank #19 by open interest · 1,392 sessions of history since Dec 1, 2020
SPXW's nearest-expiration max pain is 7,700.00 for 2026-10-05, its GEX flip is 7,651.69, net GEX is 551,683,034, its put/call open-interest ratio is 1.39. These are whole-chain derived aggregates as of Oct 2, 2026 close.
Whole-chain analytics
Derived after the close from the same dated options chain. Signed gamma exposure uses calls positive and puts negative; it is a model convention, not observed dealer inventory.
Advanced options analysis
Complete derived analysis from the dated chain, normalized where possible for comparison across tickers. Catalyst intensity measures unusual pricing and activity; it does not identify an event, predict direction, or establish that an investment is attractive.
Strongest relative signals: volume/OI 0.86 · smile convexity 25.7 pp · front IV premium 0.0 pp
SPXW closed 1.9% below its gamma max of 7,870.87. It is 1.3% above the delta neutral price of 7,623.16. Total open interest is 4,604,933, -6.5% versus the previous session. Its options catalyst-intensity score is 50.8 out of 100, led by volume/OI 0.86, smile convexity 25.7 pp, front IV premium 0.0 pp. What gamma max means · What delta neutral means
Call versus put open interest changes
Growth compares outstanding contracts on each side. A positive growth gap favors calls; a negative gap favors puts. Standardized surprises compare each measure with its own prior history. These describe the OI balance, not IV skew or buying direction.
| Measure | Value |
|---|---|
| Call OI change, 1 session | -94,796 contracts · -4.7% |
| Put OI change, 1 session | -226,596 contracts · -7.8% |
| Call minus put OI growth, 1 session | +3.1 pp |
| Call OI change, 5 sessions | -390,534 contracts · -16.8% |
| Put OI change, 5 sessions | -299,809 contracts · -10.1% |
| Call minus put OI growth, 5 sessions | -6.8 pp |
| Daily call OI change surprise | -1.16σ (250 prior changes) |
| Daily put OI change surprise | -1.16σ (250 prior changes) |
| Daily call-minus-put growth surprise | +0.79σ (250 prior changes) |
History
Hover for valuesDrag to panScroll to zoomClick a series to hide it ← → step a session+ − zoomTouch: swipe to pan, pinch to zoom, hold for the crosshair
Analysis visualizations
Derived from the 2026-10-02 options chain. Select an analysis to explore its chart.
No matching visualizations.
Gamma walls
Chart loads when this section is in view.
What followed prior gamma-max crosses?
Each historical path starts at 0% on the cross date and follows the close for ten subsequent trading sessions. Cohorts use the same direction as labelled and require gamma max to be within 10% of the close on both crossing sessions.
Crosses below gamma max 2 completed Day +10 paths · latest Aug 5, 2026
| Horizon | n | Median | Middle 50% | Above zero | Nominal ≥90% median interval | Confidence floor |
|---|---|---|---|---|---|---|
| Day +1 | 2 | -0.4% | -0.4% to -0.4% | 0% | – | – |
| Day +2 | 2 | -0.4% | -0.7% to -0.1% | 50% | – | – |
| Day +3 | 2 | -0.2% | -0.4% to +0.0% | 50% | – | – |
| Day +4 | 2 | -0.7% | -1.0% to -0.3% | 0% | – | – |
| Day +5 | 2 | -0.8% | -1.3% to -0.3% | 50% | – | – |
| Day +6 | 2 | +0.1% | -0.3% to +0.5% | 50% | – | – |
| Day +7 | 2 | -0.1% | -0.4% to +0.3% | 50% | – | – |
| Day +8 | 2 | -0.1% | -0.2% to +0.1% | 50% | – | – |
| Day +9 | 2 | +0.2% | -0.1% to +0.6% | 50% | – | – |
| Day +10 | 2 | +0.4% | +0.0% to +0.7% | 50% | – | – |
Crosses above gamma max 2 completed Day +10 paths · latest Aug 4, 2026
| Horizon | n | Median | Middle 50% | Above zero | Nominal ≥90% median interval | Confidence floor |
|---|---|---|---|---|---|---|
| Day +1 | 2 | -0.3% | -0.3% to -0.2% | 0% | – | – |
| Day +2 | 2 | -0.7% | -0.8% to -0.6% | 0% | – | – |
| Day +3 | 2 | -0.7% | -1.0% to -0.3% | 50% | – | – |
| Day +4 | 2 | -0.5% | -0.7% to -0.2% | 50% | – | – |
| Day +5 | 2 | -0.9% | -1.3% to -0.6% | 0% | – | – |
| Day +6 | 2 | -1.1% | -1.6% to -0.6% | 0% | – | – |
| Day +7 | 2 | -0.2% | -0.6% to +0.2% | 50% | – | – |
| Day +8 | 2 | -0.4% | -0.7% to +0.0% | 50% | – | – |
| Day +9 | 2 | -0.3% | -0.5% to -0.2% | 0% | – | – |
| Day +10 | 2 | -0.1% | -0.4% to +0.2% | 50% | – | – |
Returns are close-to-close after the labelled number of subsequent trading sessions. The confidence floor is the closest-to-zero bound of the order-statistic median interval; it is zero when that interval spans zero. Its coverage is nominally at least 90% under independent observations. Historical paths can overlap, so the interval and floor are descriptive uncertainty guides rather than formal coverage guarantees. Historical, not a forecast.
Last 252 sessions
| Sessions closed above gamma max | 0% |
| Gamma max crosses | 2 |
| Delta neutral crosses | 28 |
| Prior-year sessions closer to gamma max | 42.5% of 252 |
| Prior-year sessions closer to delta neutral | 47.2% of 252 |
| Open interest percentile (1y) | 42th |
| Daily open interest change versus prior year | -1.21σ (-321,392 contracts; 252 prior changes) |
| Open interest change, 5 sessions | -13.0% |
| Open interest change, 21 sessions | -11.1% |
| History available | Dec 1, 2020 → Oct 2, 2026 |
Recent crosses
- closed above delta neutral at 7,640.32 vs 7,587.17 (+0.7%)
- closed below delta neutral at 7,545.89 vs 7,571.51 (-0.3%)
- closed above delta neutral at 7,656.98 vs 7,595.15 (+0.8%)
- closed below delta neutral at 7,590.53 vs 7,612.03 (-0.3%)
- closed below gamma max at 7,736.79 vs 7,833.06 (-1.2%)
- closed above gamma max at 7,752.82 vs 7,711.82 (+0.5%)
- closed above delta neutral at 7,440.36 vs 7,395.79 (+0.6%)
- closed below delta neutral at 7,340.46 vs 7,432.88 (-1.3%)
- closed above delta neutral at 7,434.63 vs 7,420.29 (+0.2%)
- closed below delta neutral at 7,392.48 vs 7,408.11 (-0.2%)
In today's screens
- Most open interest
- Call/put contract extremes
- IV rank extremes
- Option volume activity
- Charm exposure extremes
- Volatility smile convexity extremes
- Historical payoff versus option premium
- Historically cheap call and put skew
- Unusual activity without substantial repricing
- Inexpensive forward-volatility windows
- Long-option contract scenario value
Neighbours by open interest
Cite or embed this snapshot
Share the dated 1600×840 image or cite this canonical page. The card contains public derived aggregates, not contract-level quotes.
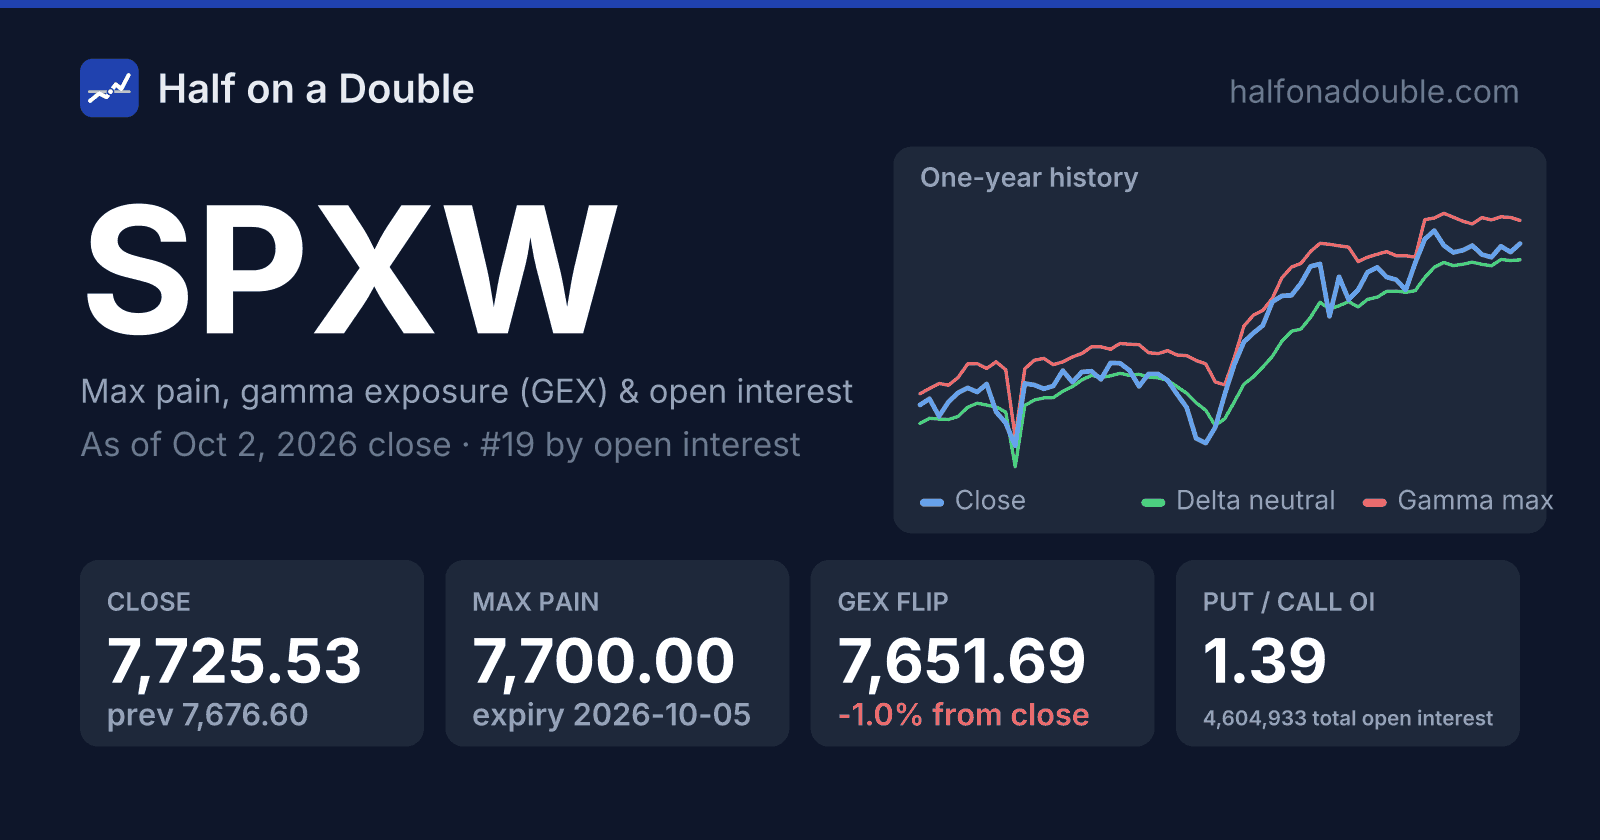
Canonical source: https://halfonadouble.com/stock/SPXW
Questions people ask about SPXW
Where is SPXW's gamma max today?
As of Oct 2, 2026, the gamma max for SPXW is 7,870.87, +1.9% from the 7,725.53 close. Gamma max is the underlying price at which the summed gamma of every open contract is largest; how it is computed and why it matters.
Is SPXW above or below its delta neutral price?
SPXW closed above delta neutral: 7,725.53 against a delta neutral price of 7,623.16. The delta neutral price is where the summed delta of the whole chain is zero; the definition.
How much open interest does SPXW have?
4,604,933 contracts of open interest across 12,980 listed contracts on Oct 2, 2026, -6.5% versus the previous session. What open interest measures.
Levels are recomputed after every trading day from licensed end-of-day options data; only derived aggregates are published. Methodology · Data and licence · Not investment advice.